Guides / Financial Planning
Average Net Worth by Age: Where Do You Stand?
Net worth is the single best snapshot of your financial health — but comparing yourself to national averages can be misleading if you do not know which number to trust. This guide breaks down median and average net worth by age using Federal Reserve data, explains what counts in the calculation, and shows you how to close the gaps.
Last updated: August 2026
TL;DR - Quick Answer
- Ages 25-34: Median net worth $39,000 | Average $120,000
- Ages 35-44: Median net worth $135,000 | Average $549,000
- Ages 45-54: Median net worth $247,000 | Average $975,000
- Use median, not average: The top 10% of households skew averages 3-4x above what most Americans actually have
Calculate your number with our Net Worth Calculator, Retirement Calculator, and Compound Interest Calculator.
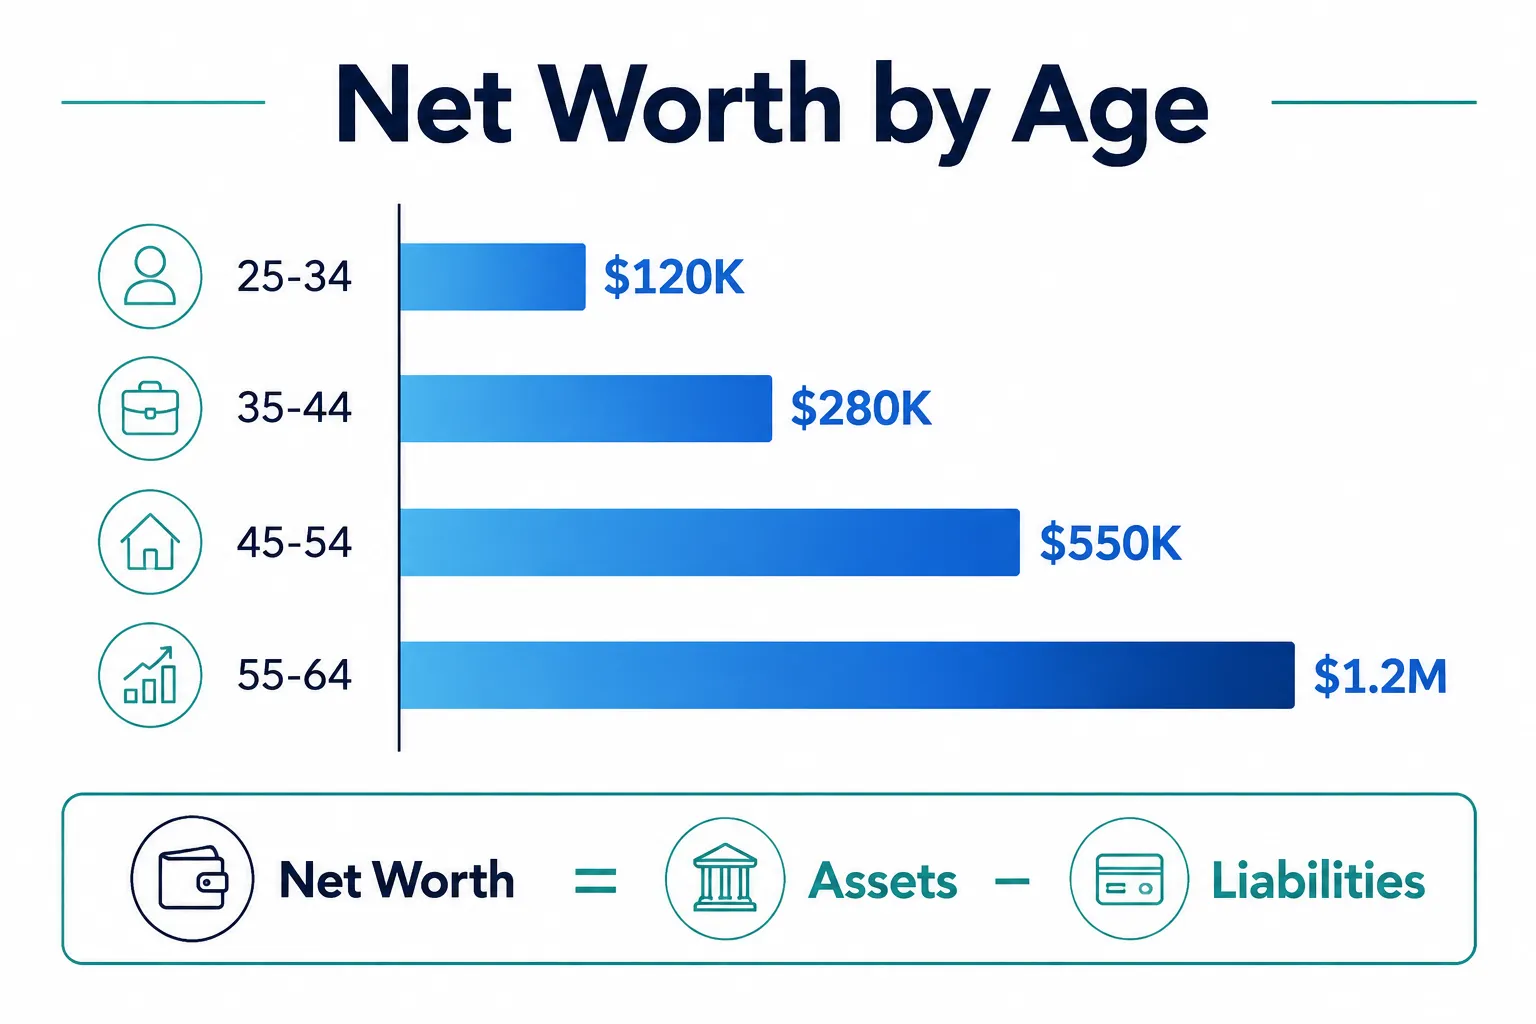
Net Worth by Age Group: Federal Reserve Data
The Federal Reserve's Survey of Consumer Finances (SCF) is the most comprehensive source of household wealth data in the United States. Conducted every three years, it surveys thousands of American families on assets, liabilities, and income. The latest published data provides these benchmarks by age group.
| Age Group | Median Net Worth | Average Net Worth |
|---|---|---|
| 25-34 | $39,000 | $120,000 |
| 35-44 | $135,000 | $549,000 |
| 45-54 | $247,000 | $975,000 |
| 55-64 | $364,000 | $1,560,000 |
| 65-74 | $409,000 | $1,790,000 |
Source: Federal Reserve Survey of Consumer Finances (SCF). Median represents the middle household — half above, half below. Average (mean) is pulled upward by high-net-worth outliers.
What These Numbers Tell You
Net worth tends to rise with age because of compound investment growth, mortgage paydown, and peak earning years. The jump from the 25-34 group (median $39,000) to the 35-44 group (median $135,000) reflects home purchases, career advancement, and a decade of retirement contributions. By ages 55-64, the median reaches $364,000 — but the average hits $1.56 million, a gap of more than $1.2 million caused by wealth concentration at the top.
Why Median vs Average Matters
If you are 40 years old and read that the "average" net worth for your age group is $549,000, you might feel behind — even if you are doing fine. That is because the average is a poor measure of what typical Americans have. A single billionaire in the sample can add millions to the average without changing the median at all.
The top 10% of US households hold roughly 65-70% of total national wealth. In the 35-44 age group, this means a small number of high-earning professionals, business owners, and inherited-wealth households pull the average to $549,000 while the typical household sits at $135,000. The ratio is even more extreme for older groups: ages 55-64 show a median of $364,000 against an average of $1.56 million — a 4.3x gap.
Compare to Median, Not Average
If your net worth is above the median for your age group, you are ahead of at least half of American households. Being below the average but above the median is completely normal — and does not mean you are failing financially.
When Average Is Useful
Average net worth is relevant if you are studying total national wealth, analyzing tax policy, or comparing aggregate savings across decades. For personal benchmarking, always use the median. Financial planners typically recommend comparing net worth to 1x, 2x, or 3x your annual salary by certain milestone ages — a more actionable framework than national averages.
What Counts in Net Worth
Net worth is a simple formula: Assets minus Liabilities. What you own minus what you owe. Income is not included — only accumulated wealth and outstanding debt.
Assets (What You Own)
- Home equity: Market value minus remaining mortgage balance
- Retirement accounts: 401(k), 403(b), traditional IRA, Roth IRA, pension balances
- Taxable investments: Brokerage accounts, index funds, individual stocks and bonds
- Cash and savings: Checking, savings, money market, CDs, HYSA balances
- Other assets: Vehicle value, business equity, rental property equity, collectibles (at realistic resale value)
Liabilities (What You Owe)
- Mortgage: Remaining principal on primary and secondary homes
- Student loans: Federal and private education debt
- Auto loans: Outstanding car loan balances
- Credit card debt: Revolving balances (pay these off first)
- Other debt: Personal loans, medical debt, home equity lines of credit (HELOC)
Common Mistakes When Calculating Net Worth
Do not count your gross annual salary — income flows through net worth only when you save or invest it. Do not use the original purchase price of your home; use current market value. Include all retirement accounts even if you cannot access them until 59½ — they are real assets. On the liability side, include every outstanding balance, not just monthly payments.
Example: $480,000 assets - $188,000 liabilities = $292,000 net worth
Case Study: Marcus and Jen, Both 38, in Minneapolis
Household Profile
- Ages: Both 38 (35-44 age group)
- Combined income: $155,000/year
- Marcus: Marketing manager, $82,000
- Jen: Registered nurse, $73,000
- Location: Minneapolis, MN
- Married, one child (age 4)
Benchmark Comparison
- Median net worth (35-44): $135,000
- Average net worth (35-44): $549,000
- Their net worth: $292,000
- vs median: +$157,000 (116% above median)
- vs average: -$257,000 (47% below average)
- Salary benchmark (2x income): $310,000 target
Asset Breakdown
- Home value: $480,000 | Mortgage owed: $185,000 | Equity: $295,000
- Marcus 401(k): $68,000 | Jen 401(k): $47,000 | Total: $115,000
- Roth IRAs (combined): $18,000
- Taxable brokerage: $14,000
- Emergency fund (HYSA): $10,000
- Vehicles (2 cars, paid off): $28,000
- Total assets: $480,000
Liability Breakdown
- Mortgage: $185,000
- Student loans (Jen): $3,000
- Total liabilities: $188,000
- Net worth: $480,000 - $188,000 = $292,000
Gap Analysis
Marcus and Jen are in a strong position compared to the median — their $292,000 net worth is more than double the $135,000 median for their age group. However, they fall well short of the $549,000 average, which is expected given that average is skewed by high-wealth households. Against the common planner rule of 2x annual income by 40, they are $18,000 short of the $310,000 target with two years to close the gap.
Their biggest vulnerability is concentration in home equity: $295,000 of their $292,000 net worth (101%) is tied up in their house. Retirement accounts total $133,000 — below the $155,000-$310,000 range recommended for their income level. Taxable investments at $14,000 provide almost no flexibility for mid-term goals or early retirement bridge funding.
Recommended Actions
- 1. Max both 401(k)s — at $23,500 each ($47,000 combined), they are currently contributing ~$22,000 total. Closing this gap adds $25,000/year in tax-advantaged savings.
- 2. Pay off Jen's remaining $3,000 student loan — small balance, but eliminating it frees cash flow and removes a liability line item.
- 3. Build taxable brokerage to $50,000 — target $800/month into a low-cost index fund for flexibility beyond retirement accounts.
- 4. Avoid upgrading the house — resist lifestyle inflation; their home equity is already their largest asset class.
- 5. Track quarterly — use the Net Worth Calculator to monitor progress toward the $310,000 target by age 40.
How to Increase Net Worth at Any Age
Net worth grows through a combination of saving, investing, debt reduction, and asset appreciation. The strategies below work at every life stage — the priorities just shift depending on where you are in the wealth-building timeline.
Eliminate high-interest debt first
Credit card debt at 20-25% APR destroys net worth faster than any investment can build it. Paying off a $8,000 balance at 22% APR saves $1,760/year in interest — a guaranteed return no index fund can match. After credit cards, tackle auto loans above 7% and private student loans above 6%.
Max retirement accounts every year
In 2026, contribute the maximum to your 401(k) ($23,500), IRA ($7,000), and HSA if eligible ($4,300 individual / $8,550 family). A couple maxing both 401(k)s saves $47,000/year in tax-advantaged accounts alone. Over 20 years at 7% returns, that is roughly $2.1 million — use our Compound Interest Calculator to model your timeline.
Build home equity strategically
Homeownership builds net worth through mortgage principal paydown and long-term appreciation. The median homeowner aged 35-44 holds significantly more net worth than renters at the same age. But do not over-concentrate — if home equity exceeds 60-70% of total net worth, prioritize investment accounts to diversify.
Avoid lifestyle inflation
Every raise, bonus, and promotion is an opportunity to increase savings rate — not spending. Households that maintain a fixed budget through income growth of $10,000/year and invest the difference add $100,000+ to net worth over a decade, assuming 7% returns. The difference between saving 15% and 25% of income over a career can mean $500,000-$1,000,000 in additional net worth at retirement.
Net Worth Targets by Age (Salary-Based Rule of Thumb)
Financial author Thomas J. Stanley and many planners recommend these multiples of annual income as net worth milestones. They adjust for individual circumstances better than national medians.
| Age | Target Net Worth | Example ($75K Income) |
|---|---|---|
| 30 | 1x annual salary | $75,000 |
| 40 | 2x annual salary | $150,000 |
| 50 | 4x annual salary | $300,000 |
| 60 | 6x annual salary | $450,000 |
| 67 (retirement) | 8-10x annual salary | $600,000 - $750,000 |
Calculate Your Net Worth
Stop guessing where you stand. Enter your assets and liabilities to see your net worth, compare it to age-group benchmarks, and project how your wealth grows over time.
Frequently Asked Questions
What is the average net worth by age in the United States?
According to the Federal Reserve Survey of Consumer Finances (SCF), average net worth by age group is approximately: $120,000 for ages 25-34, $549,000 for ages 35-44, $975,000 for ages 45-54, $1.56 million for ages 55-64, and $1.79 million for ages 65-74. These averages are heavily skewed by high-wealth households — median figures are much lower and better represent the typical American.
What is a good net worth at 35?
The median net worth for Americans aged 35-44 is $135,000, according to Federal Reserve SCF data. A net worth above $135,000 puts you ahead of half your peers. Financial planners often suggest having 1-2 times your annual salary saved by 35 — so on a $75,000 income, a target of $75,000-$150,000 is reasonable. Home equity and retirement accounts typically make up the bulk of net worth at this age.
Why is median net worth so much lower than average net worth?
The top 10% of households hold roughly 65-70% of total US wealth. When you calculate the average (mean), a handful of billionaires and multi-millionaires pull the number dramatically upward. For example, the average net worth for ages 35-44 is $549,000, but the median is only $135,000 — meaning half of households in that age group have less than $135,000. The median is the more useful benchmark for comparing yourself to typical Americans.
What counts toward net worth?
Net worth equals total assets minus total liabilities. Assets include home equity (home value minus mortgage), retirement accounts (401(k), IRA, pension), taxable investments, cash and savings, and vehicle value. Liabilities include mortgages, student loans, auto loans, credit card debt, and personal loans. Annual income is not part of net worth — only what you have accumulated and owe.
How can I increase my net worth quickly?
The fastest levers are eliminating high-interest debt (credit cards at 20%+ APR), maximizing employer-matched retirement contributions, and avoiding lifestyle inflation as income rises. Building home equity through mortgage payments and appreciation helps, but diversification into retirement and taxable investment accounts reduces concentration risk. Use our Net Worth Calculator to track progress and our Compound Interest Calculator to project growth.
Related Guides
How to Start Investing with $1,000: A Beginner's Step-by-Step Guide
Start investing with just $1,000. Learn which account to open, what to buy (VTI, VOO, VTSAX), and how $100/month grows to six figures over time.
How to Save $50,000 in 3 Years: A Realistic Plan
A step-by-step plan to save $50,000 in 3 years on an average salary. Includes monthly targets, budget breakdowns, a real case study, and strategies that actually work.